ServicesBox Truck Insurance
Box Truck Insurance in Cedar Hill
We start by learning how your box truck actually earns its money: the freight, the contracts, the radius and who drives. Then we build coverage around that picture, so your certificate clears the shipper and a claim lands where you expected.
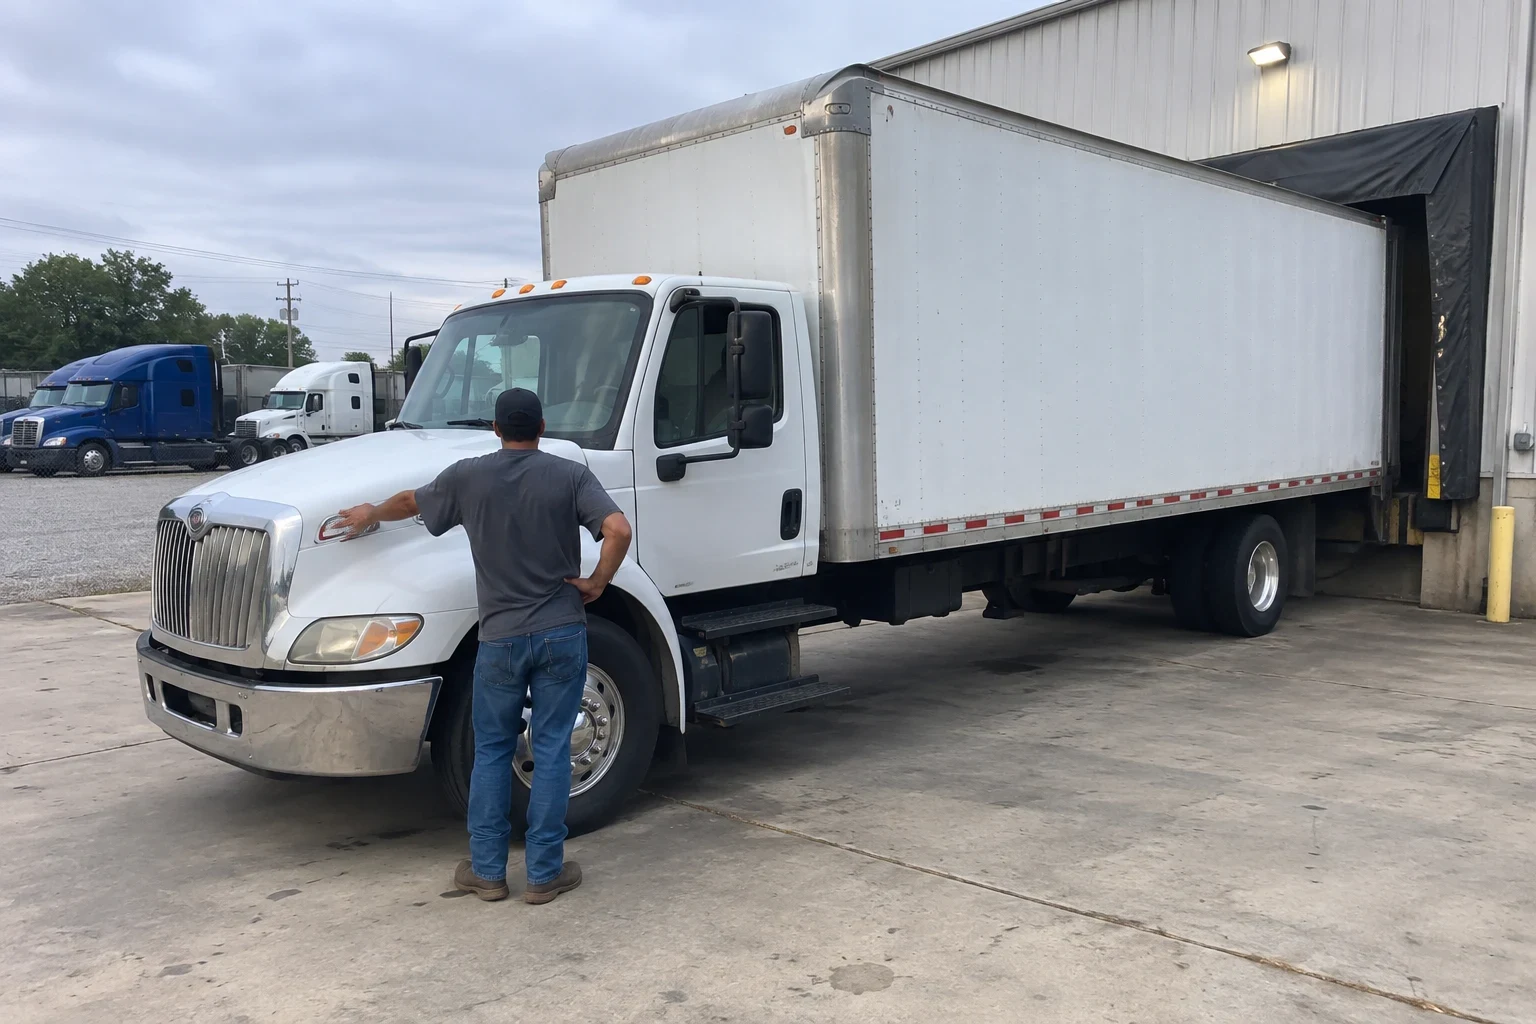
Coverage that starts with how you run the truck
A box truck can be a last-mile delivery van one month and a furniture or appliance hauler the next. Each kind of work carries a different risk, and each contract asks for different limits. A policy written for general freight can leave gaps if you start hauling refrigerated product or doing white-glove inside delivery.
So before we quote anything, we ask the questions an underwriter will ask anyway. What do you haul, how far, under whose authority, and what does your contract require on the certificate of insurance. Getting those answers right first means fewer midterm changes, fewer surprise exclusions and a premium that reflects your real operation.
Many box truck owners around Cedar Hill run under 26,001 pounds and drive without a CDL. That is fine for the truck, but it changes how carriers look at driver experience, and we explain that plainly.
What a box truck policy can include
- Primary auto liability
- Covers injury and property damage you cause to others on the road. If you run for hire across state lines under your own MC authority, we handle the federal filings that go with it.
- Motor truck cargo
- Protects the freight in the box. We read the cargo form for exclusions that catch box truck operators, such as unattended vehicle rules, electronics limits and refrigeration breakdown.
- Physical damage
- Comprehensive and collision for the truck itself. We set the stated value from what the truck is really worth, including the liftgate and box body, so a total loss pays what you need.
- General liability
- Many shippers and receivers ask for it because box truck work often means loading docks, inside delivery and time on someone else's property.
- Non-trucking liability
- If you lease onto another carrier, their policy covers you under dispatch. Non-Trucking Liability (Bobtail) Insurance fills the hours when you are off dispatch.
Signs your box truck coverage needs a closer look
A contract asked for limits you don't carry
Delivery programs and brokers often require specific liability and cargo amounts, plus an endorsement that names them on your policy. If your certificate keeps getting sent back, the policy may not match the work.
Your freight has changed
Moving from parcels to appliances, or adding a reefer unit, changes the cargo risk. Your existing form may not respond the way you think.
You added a driver
Someone not listed on the policy can mean a denied claim. Non-CDL drivers with limited commercial experience also get rated differently, and it is better to know before they take the keys.
You're getting your own authority
Leaving a lease to run under your own DOT number and MC authority moves liability onto your policy. That shift is worth planning for a few weeks ahead.
Your renewal jumped with no explanation
A premium increase has a cause, whether it is a loss, a ticket, a radius change or the market. We find which one it is before we shop.
How we put your policy together
- 1
A working conversation
We talk by phone, by video or at our office. You tell us about your trucks, drivers, freight and routes, and we ask the follow-up questions that matter to underwriters.
- 2
Contract and document review
Send us the insurance requirements from your shipper or broker, your current declarations page and your driver list. We match each requirement to a coverage line so nothing gets missed.
- 3
Quotes explained line by line
We bring back options and walk through what each one covers, what it excludes and how the deductibles work. You choose with the full picture in front of you.
- 4
Filings and certificates
Once you bind, we file what your authority requires and issue certificates of insurance to the parties who need them. Later changes, like a new truck or driver, come through the same call.
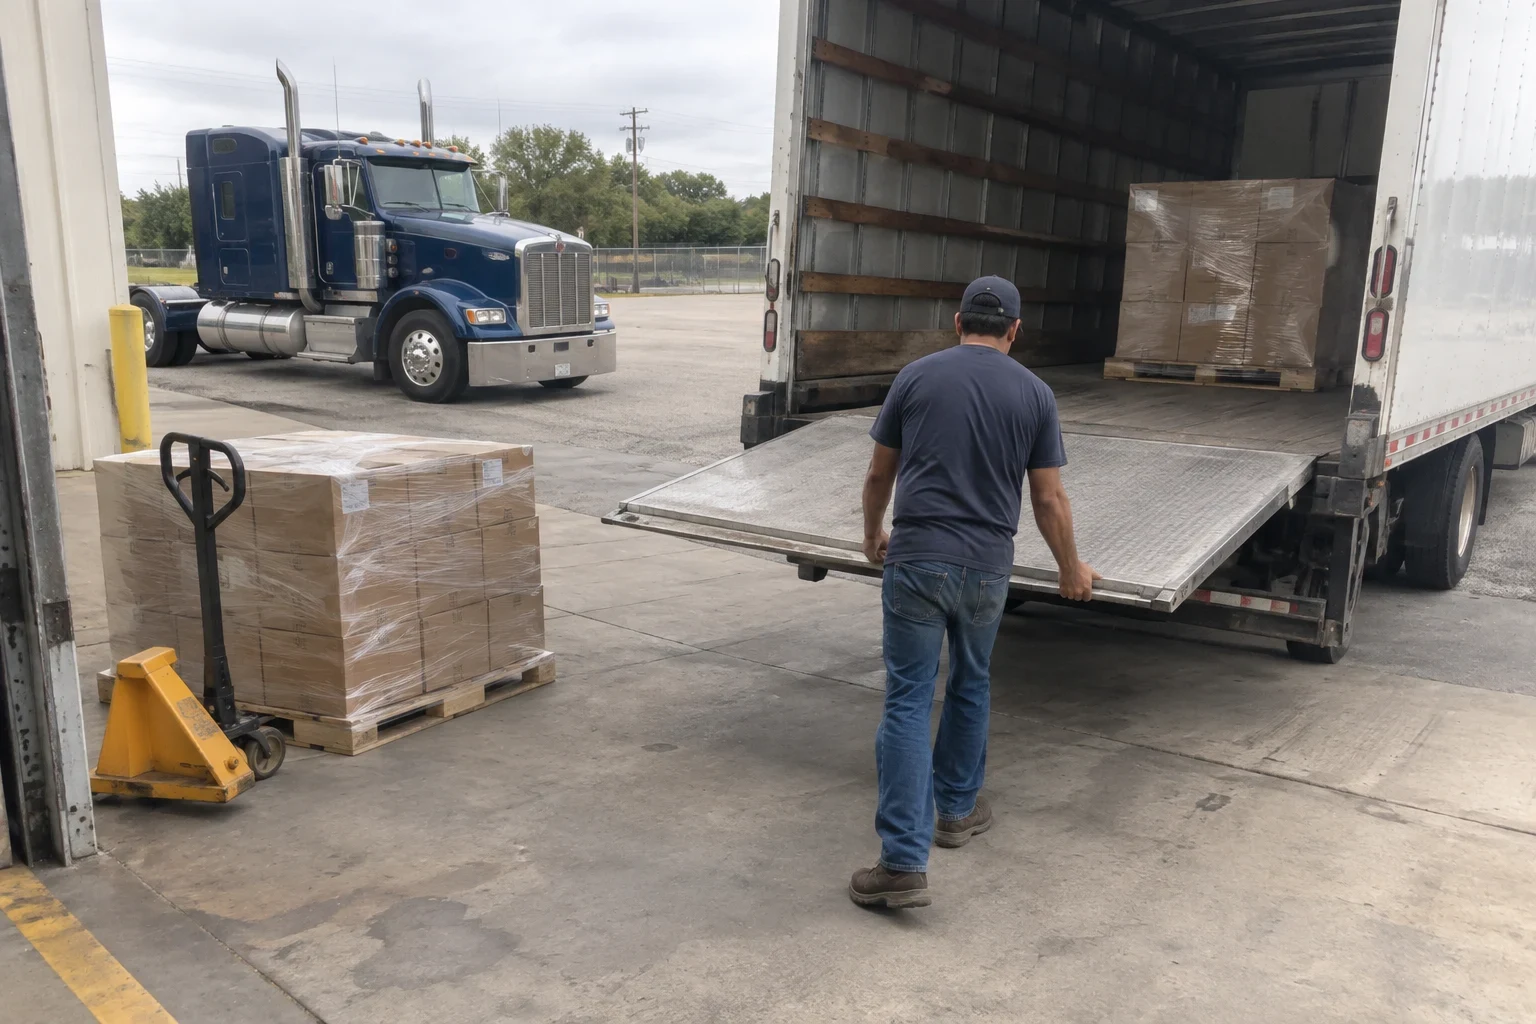
What shapes your box truck premium
Box truck pricing varies more than most owners expect, because two trucks of the same size can do very different work. We go over each factor that applies to you, so you know why the number is what it is. There are no flat rates in this line of insurance.
- Radius and routes
- Local runs inside the metro rate differently from regional or interstate work. Dense delivery routes with many stops carry their own exposure.
- What you haul
- Electronics, refrigerated food and high-value goods raise cargo cost. General freight and packaged goods usually sit lower.
- Drivers and their records
- Age, years of commercial driving and the motor vehicle record of every listed driver weigh heavily. One clean, experienced driver can change the picture.
- Truck value and limits
- The stated value of the truck, the liability and cargo limits your contracts call for, and the deductibles you choose all move the premium.
- Authority age and loss history
- Newer authorities and recent claims draw closer underwriting. A few years of clean operation opens more markets.
Box truck insurance questions
Something not covered here? (972) 526-0372
My box truck doesn't need a CDL. Do I still need commercial insurance?
Yes, if the truck is used for business. A personal auto policy will usually exclude for-hire or commercial delivery work. The CDL rules and the insurance rules are separate, so we look at how the truck is used, not just its weight.
Do I need my own MC authority to run a box truck?
Not always. Many owners lease onto a carrier or work for a delivery partner under that company's authority. Others run their own DOT number and MC authority for interstate for-hire freight, and a Texas-only operation may have state requirements instead. We sort out which applies before quoting, because it decides who carries the primary liability.
Is my liftgate covered if it breaks?
Physical damage coverage can include the liftgate if it is part of the stated value and the damage comes from a covered event, such as a collision. Mechanical wear and breakdown are generally not covered. We list the liftgate and box body in the valuation so they aren't left out.
Can you match the insurance requirements from my delivery contract?
That is usually the first thing we look at. Send us the requirement sheet and we compare it to the policy line by line, including limits, the endorsement that names the shipper or broker on your policy, and any waiver language. Then we quote coverage that meets it.
How soon can I get a certificate of insurance?
Certificates are issued once the policy is bound and the carrier confirms coverage. Timing depends on the carrier and how complete your information is. Having your driver list, VIN and contract requirements ready speeds things along.
Talk through your box truck operation
Tell us what you haul and who you haul it for. We will find the right coverage for that work and explain your quote clearly, whether you run out of Cedar Hill or the towns around it.