ServicesDump Truck Insurance
Dump Truck and Construction Truck Insurance in Cedar Hill
Dump and construction trucks live a different life than over-the-road rigs. Short hauls, rough job sites, raised beds and contracts with their own insurance demands. We look at how your trucks actually work before we quote, so the policy covers the risks you really carry.
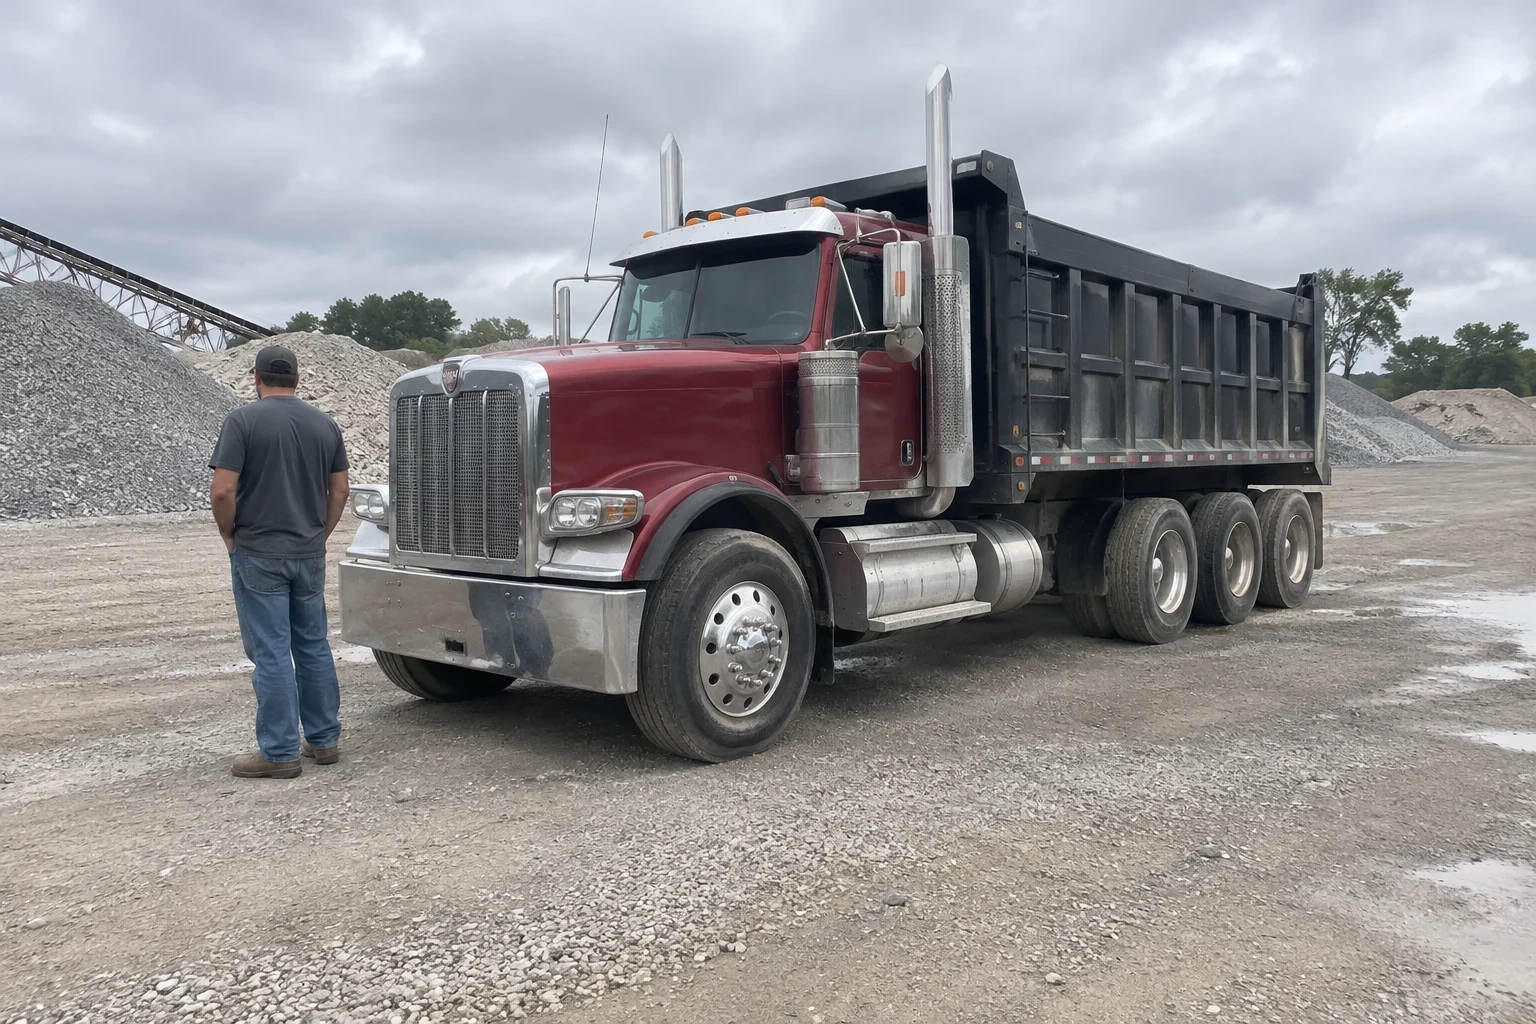
Coverage shaped around the work, not the truck type
A dump truck hauling base rock to a subdivision faces different risks than one carrying demolition debris to a landfill or running asphalt for a paving crew. Insurers price those jobs differently, and a policy written for the wrong one can leave gaps that only show up after a loss. So our first conversation is about your operation: what you haul, who you haul for, how far you run and where the truck spends its day.
From there we put together the pieces that fit. That usually starts with primary auto liability and physical damage on the truck and dump body, and often adds general liability for job-site work. Some operations also need cargo coverage or non-trucking liability. If you run under your own MC authority, lease onto a carrier or work strictly intrastate, the filings and limits change, and we sort that out before anything is bound.
What a dump truck policy can include
- 01
Primary auto liability
Covers injury and property damage you cause to others while operating your trucks. This is the coverage most contracts and filings are built on, and the limits your general contractors ask for drive a lot of the decision.
- 02
Physical damage on the truck and body
Collision and comprehensive for the chassis, the dump body and the hoist. We make sure the stated value reflects the full rig, since a newer body or an upfitted mixer drum can be worth far more than the cab alone suggests.
- 03
General liability for job sites
Auto policies are written around driving. When your truck is parked and dumping, spreading or backing around a site, general liability is often what responds to damage to a slab, a curb or someone else's equipment.
- 04
Cargo coverage where it applies
Many haulers of dirt and aggregate do not need it. If you haul materials owned by a customer, such as equipment or finished product, we check whether your contracts expect cargo coverage.
- 05
Certificates and endorsements
Naming the general contractor on your policy, waivers of subrogation and primary and noncontributory wording are common on construction contracts. We read what your contract requires and get the matching certificate of insurance issued.
Questions about Dump Truck Insurance?
Call(972) 526-0372Signs your current coverage needs a closer look
A contractor rejected your certificate
This usually means a missing endorsement or a limit that falls short of the contract. It is fixable, but it should be fixed correctly rather than patched for one job.
Your hauling changed but your policy did not
Moving from aggregate to demolition debris, or from local runs to longer hauls, changes how insurers see the risk. A policy written for your old work may not respond the way you expect.
You added a truck or a new body
New equipment that never made it onto the schedule, or a value that was never updated, is one of the most common reasons a physical damage claim pays less than the owner thought.
You are unsure what covers a site accident
If a raised bed clipped a power line or a tailgate damaged a foundation, would your auto policy or general liability respond. If you cannot answer that clearly, we should talk.
Your renewal jumped with no explanation
A premium increase has a reason, whether it is a claim, a driver record or a market shift. We find out which one before suggesting any changes.
How we put your coverage together
- 1
A conversation about your operation
By phone, video or at our office, we ask about your trucks, drivers, loads, radius and the contracts you work under. Having your current declarations page and a sample contract handy makes this go faster.
- 2
Finding the real exposures
We compare how you work against how your coverage is written. Gaps, overlaps and missing endorsements get noted plainly, with an explanation of why each one matters.
- 3
Quotes from markets that write this class
Not every insurer is comfortable with dump and construction work. We approach the ones that are and lay out the options side by side, line by line.
- 4
Binding, filings and certificates
Once you choose, we bind the policy, handle any required filings for your DOT number or authority, and send the certificates of insurance your contractors need.
What shapes your premium
Dump truck coverage is priced on the details of your operation, so two trucks of the same model can carry very different premiums. We explain which factors are moving your number and which ones you can actually influence. You get your quote by phone once we understand the work.
- What you haul and where
- Aggregate, dirt, asphalt and demolition debris carry different risk profiles. Landfill runs and tight urban job sites are rated differently from open-road hauls.
- Radius of operation
- Local work within a short radius is often priced differently than longer runs. Whether you stay in Texas or cross state lines also affects filings and limits.
- Drivers and their records
- Driver age, experience in dump trucks and motor vehicle records weigh heavily. A single new hire with violations can change a small fleet's premium.
- Truck value and equipment
- Physical damage cost follows the value of the chassis, body and any upfit. Older trucks may warrant a different approach than new ones.
- Contract requirements and loss history
- Higher limits and added endorsements cost more. Your claims history and time in business also factor into what markets will offer.
Questions dump truck owners ask us
Do I need cargo coverage if I only haul dirt and gravel?
Often not, since low-value bulk material is rarely what an insurer or contractor worries about. Some contracts still require it, and some loads are owned by the customer. We read your agreements and tell you honestly whether it is worth carrying.
Does my auto policy cover damage while I am dumping on a job site?
It depends on the policy wording and what happened. Auto coverage is built around the use of the vehicle, while general liability typically handles site operations. We check how your policies fit together so an accident does not fall between them.
My contract says the general contractor must be named on my policy, with a waiver of subrogation. Can you handle that?
Yes, those requests are common on construction work around Cedar Hill and the surrounding area. We confirm the endorsements are actually on your policy, not just typed onto a certificate, and then issue the certificate of insurance to the contractor.
Should I run under my own authority or lease onto a carrier?
Both work, and the insurance looks different for each. Under a lease, the carrier may provide primary liability while you carry physical damage and non-trucking liability. Under your own authority, you carry the full package and the filings. We walk through what each means for your cost and your obligations.
Can you set up coverage on a dump truck I am about to buy?
Yes. Call before the purchase closes and have the VIN, body details and price ready. We can show you what the coverage will look like so there are no surprises once the truck is yours.
Let's look at how your trucks really work
A short conversation about your loads, drivers and contracts is enough for us to spot gaps and build a quote that fits. We serve haulers in Cedar Hill, Midlothian, Red Oak and nearby towns.